100 milliseconds, 4 hops: The invisible journey of your UPI payment
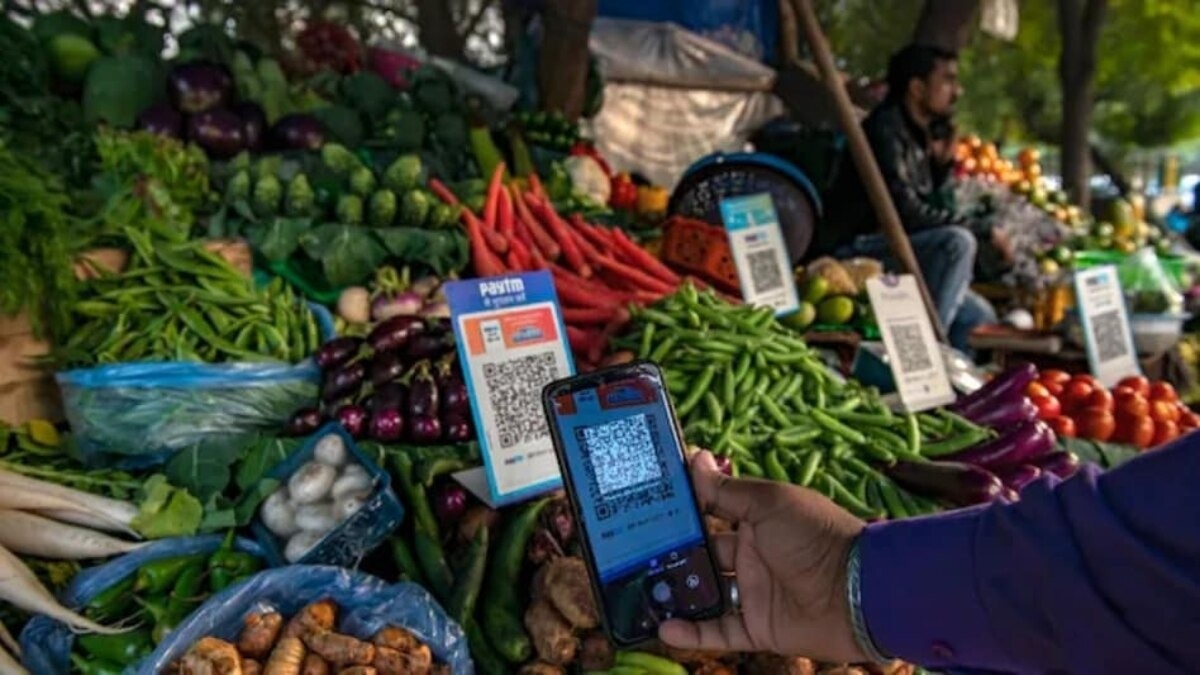
The little soundbox clipped to the vegetable cart chirps out its verdict, “Paytm par pachaas rupaye praapt huye. Paytm karo,” and the vendor barely glances up. You walk away without a second thought.
This is UPI in its most ordinary hour, so woven into an Indian street or grocery shop that nobody stops to marvel at it any more. In the half-second between your thumb leaving the screen and that chime sounding, money has vanished from your account and reappeared in a stranger’s, and neither of you sees any part of the journey the money actually takes to get there.
Follow that vanishing rupee, not the padlock guarding it but the road it actually travels, and you find one of the tightest relay races on earth. Four runners are passing a baton, none of them are permitted to drop, and all finish before you have put your phone back in your pocket.WHO ARE THE FOUR RUNNERS IN THIS RELAY?
Picture the transaction as a message passed hand to hand through a small, disciplined crowd, each person allowed to do exactly one job and no more.
The first runner is your bank, called the remitter bank in the industry’s own dry vocabulary, though I rather like to think of it as the guardian of your money.
The second is the National Payments Corporation of India, or NPCI, the switchboard operator who never actually touches a rupee but knows exactly where every rupee is supposed to go.
The third is the shopkeeper’s bank, or the beneficiary bank, waiting patiently at the other end of the line.
And the fourth, easy to forget, is the mobile network itself, the invisible courier that finally taps the shopkeeper's soundbox on the shoulder and tells it what to say.
Four handoffs, four separate computer systems, and all of them expected to agree with each other in the time it takes you to exhale.WHAT HAPPENS THE INSTANT YOU ENTER YOUR PIN?
The moment your thumb presses that final digit, your phone does something almost ceremonial. It seals your payment instructions inside an encrypted packet, a kind of digital envelope that only your bank holds the key to, and sends it flying towards NPCI's servers.
NPCI does not linger to admire the envelope. It reads only the address on the outside, works out which bank the money is leaving and which bank it is arriving at, and forwards a debit request to your bank within a matter of milliseconds.
Your bank, in turn, checks two things and two things only. Is this really you, and do you actually have the money you are promising? If both answers are yes, it sets that amount aside, marks it as spoken for, and sends NPCI a short, clean signal back. Approved.
That signal alone is not the money moving. It is closer to a promise, notarised and time-stamped, that the money is now on its way.HOW DOES THE PROMISE ACTUALLY BECOME MONEY?
Here is where the elegance of the whole design reveals itself, because at no point does anyone physically move a rupee down a wire.
NPCI takes your bank’s approval and turns it into an instruction for the shopkeeper’s bank: credit this amount, to this account, right now. The beneficiary bank checks that the account is real and open, credits the sum, and sends its own short confirmation back up the same chain.
What has actually happened, underneath all the ceremony, is that two banks have simply agreed to update their own ledgers in matching amounts, one going down, the other going up, and NPCI has spent the entire transaction acting as a scrupulously honest witness to that agreement. The money did not travel. The permission to believe in a new balance did.
That belief is not left to chance, however. Behind the scenes, the two banks' own accounts, the ones they themselves hold with the Reserve Bank of India, are later adjusted to match, so the money each bank now owes the other is actually settled, not merely assumed.
Your bank statement’s new balance, in other words, is not a polite fiction. It is backed, quietly and a little after the fact, by real funds actually changing hands between banks.
Only once that full loop closes, bank to NPCI to bank and back again, does a final signal race down the mobile network to the shopkeeper’s soundbox, and it obediently announces your generosity to the whole street, in whichever language and phrasing the app has taught it to use.WHY DOES THIS HAPPEN SO FAST?
The honest, unglamorous answer is fibre optic cable, laid in such straight, uncluttered lines between banks and NPCI’s data centres that a request can complete its entire round trip, bank, switch, bank, switch, in a window most engineers describe as two to five seconds, and often less.
What crosses that cable is not a bundle of financial paperwork. It is a few hundred bytes of tightly compressed text, no heavier than a text message, asking a single yes-or-no question and expecting a single yes-or-no answer.
Speed, in other words, is not the product of some single dazzling invention. It is the product of asking the smallest possible question of the smallest possible number of computers, and refusing to let any of them politely wait their turn.advertisementWHY DOES UPI SOMETIMES FAIL, AND WHOM SHOULD YOU BLAME?Almost never your password, and almost never a thief. The far more mundane truth is that this elegant four-step relay has a weak link precisely where every relay does, in the handoff.
Consider what actually happened on a single evening in March this year, when UPI stumbled nationwide as banks rushed to close their books for the financial year. So many requests arrived at once that one essential lookup service, the internal address book matching your UPI ID to your actual account, saw its processing load climb past 95 per cent, and a task that should finish in about 50 milliseconds began, at moments, taking longer than two full seconds. Multiply that lag across millions of simultaneous transactions, and an entire country's evening shopping quietly seizes up.
The scale here is almost impossible to hold in your head honestly. NPCI's own systems now process more transactions in a single day than some countries manage in a year, and industry estimates suggest that for every single second UPI stays down, something in the neighbourhood of 7,000 transactions, worth roughly a crore of rupees, simply stalls mid-flight.
That is not a security failure. It is closer to a highway built beautifully for ordinary traffic, suddenly asked to carry a festival crowd, and briefly, understandably, buckling at its narrowest junction.WHAT SHOULD YOU ACTUALLY TAKE AWAY FROM ALL THIS?
The next time that little voice announces your payment, and you walk off without a second glance, spare half a thought about what you have just asked of the world. In under five seconds, an encrypted request crossed a switch built to serve a billion and a half people, was interrogated twice, approved twice, and echoed back through a mobile tower to a small speaker clipped to a cart of vegetables.
Nothing about that journey was magic. It was merely engineering, disciplined enough to feel like magic, four strangers passing a baton in the dark and never once dropping it.
That, in the end, is the real trick behind the chime. Not that the money moved instantly, but that four separate, unrelated, occasionally overwhelmed institutions agreed, in near-perfect unison, to believe the same small lie together: that a number in one ledger could vanish and reappear, faithfully, in another.- EndsPublished By: Radifah KabirPublished On: Sep 18, 2026 13:53 IST