Almost one out of 100 homebuyers in negative equity, RBA says
The risk to Australia from a major global financial shock is growing as the purchasing power of households is eroded by high inflation, the Reserve Bank has warned.
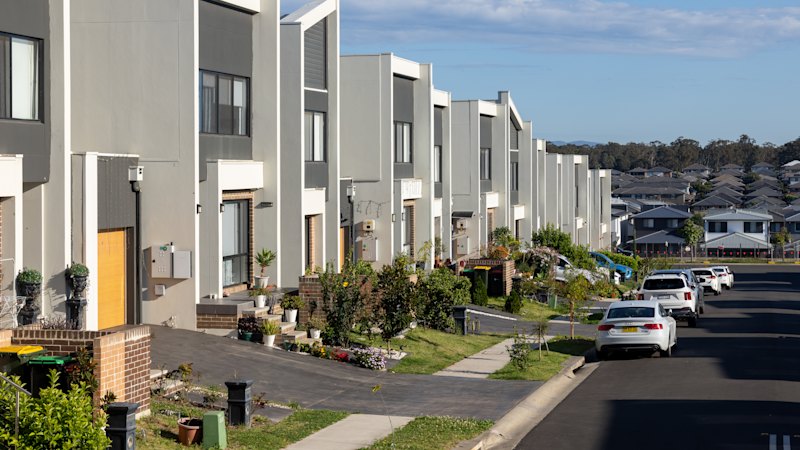
The bank flagged on Thursday that first home buyers – including users of the 5 per cent deposit scheme – were most likely to be in negative equity as property prices sink and interest rates increase.
Around 5 per cent of home borrowers would be at risk of defaulting on their loans if inflation increases to 7 per cent.Sitthixay DitthavongA shift in sentiment towards the AI investment boom, which is increasingly debt-funded and fuelled by expectations of rapid earnings growth, is also a potential trigger for international economic turmoil, according to the RBA’s twice-yearly review of financial stability.
“Threats to international financial stability continue to mount,” the report said.
While less than 1 per cent of home borrowers are in negative equity – where the amount they owe on their loan is more than the value of their property – the banks said recent property buyers were most likely to be in negative equity.
“This includes first home buyers participating in the Australian government 5 per cent deposit scheme,” the report said.
Just over 100,000 first home buyers have used the 5 per cent deposit scheme since last October when Labor opened it up to those on higher incomes.
Australia’s income per person – after tax and interest payments and adjusted for inflation – declined over the first half of 2026 due to higher inflation and increases in interest rates.
“All households’ budgets have been affected by high inflation eroding purchasing power,” the report said.
“However, this is more likely to cause stress for lower-income households, many of whom are renters, because their expenses tend to make up a larger share of their disposable income.”
It also warned the debt-financing cycle underpinning investment in AI is becoming more opaque and circular.
House prices in Australia have been falling after multiple interest rate hikes this year, along with changes to the taxation of housing investment and lingering economic uncertainty caused by conflict in the Middle East.
An RBA “scenario analysis” showed in the event of an overseas economic shock – where the unemployment rate increases to 6.3 per cent, inflation increases to 7 per cent and the cash rate rises to 5.6 per cent – the share of home borrowers at a higher risk of defaulting on their loans was estimated to increase to around 5 per cent, only a little higher than the last peak in 2023.
In this scenario, around two-thirds of these borrowers are estimated to have insufficient income to cover their expenses but have enough buffers to service their debts and essential expenses for at least six months.
But in a scenario where housing prices were to decline by a further 20 per cent, “few households are in negative equity”.
On Tuesday, the Reserve Bank lifted official interest rates by 0.25 of a percentage point to a 15-year high of 4.6 per cent in a bid to dampen inflationary pressures in the economy. That followed hikes in February, March and May.
Cut through the noise of federal politics with news, views and expert analysis. Subscribers can sign up to our weekly Inside Politics newsletter.
You have reached your maximum number of saved items.
Remove items from your saved list to add more.