China’s US$33 billion experiment to prop up property market sputters on weak demand - The Business Times
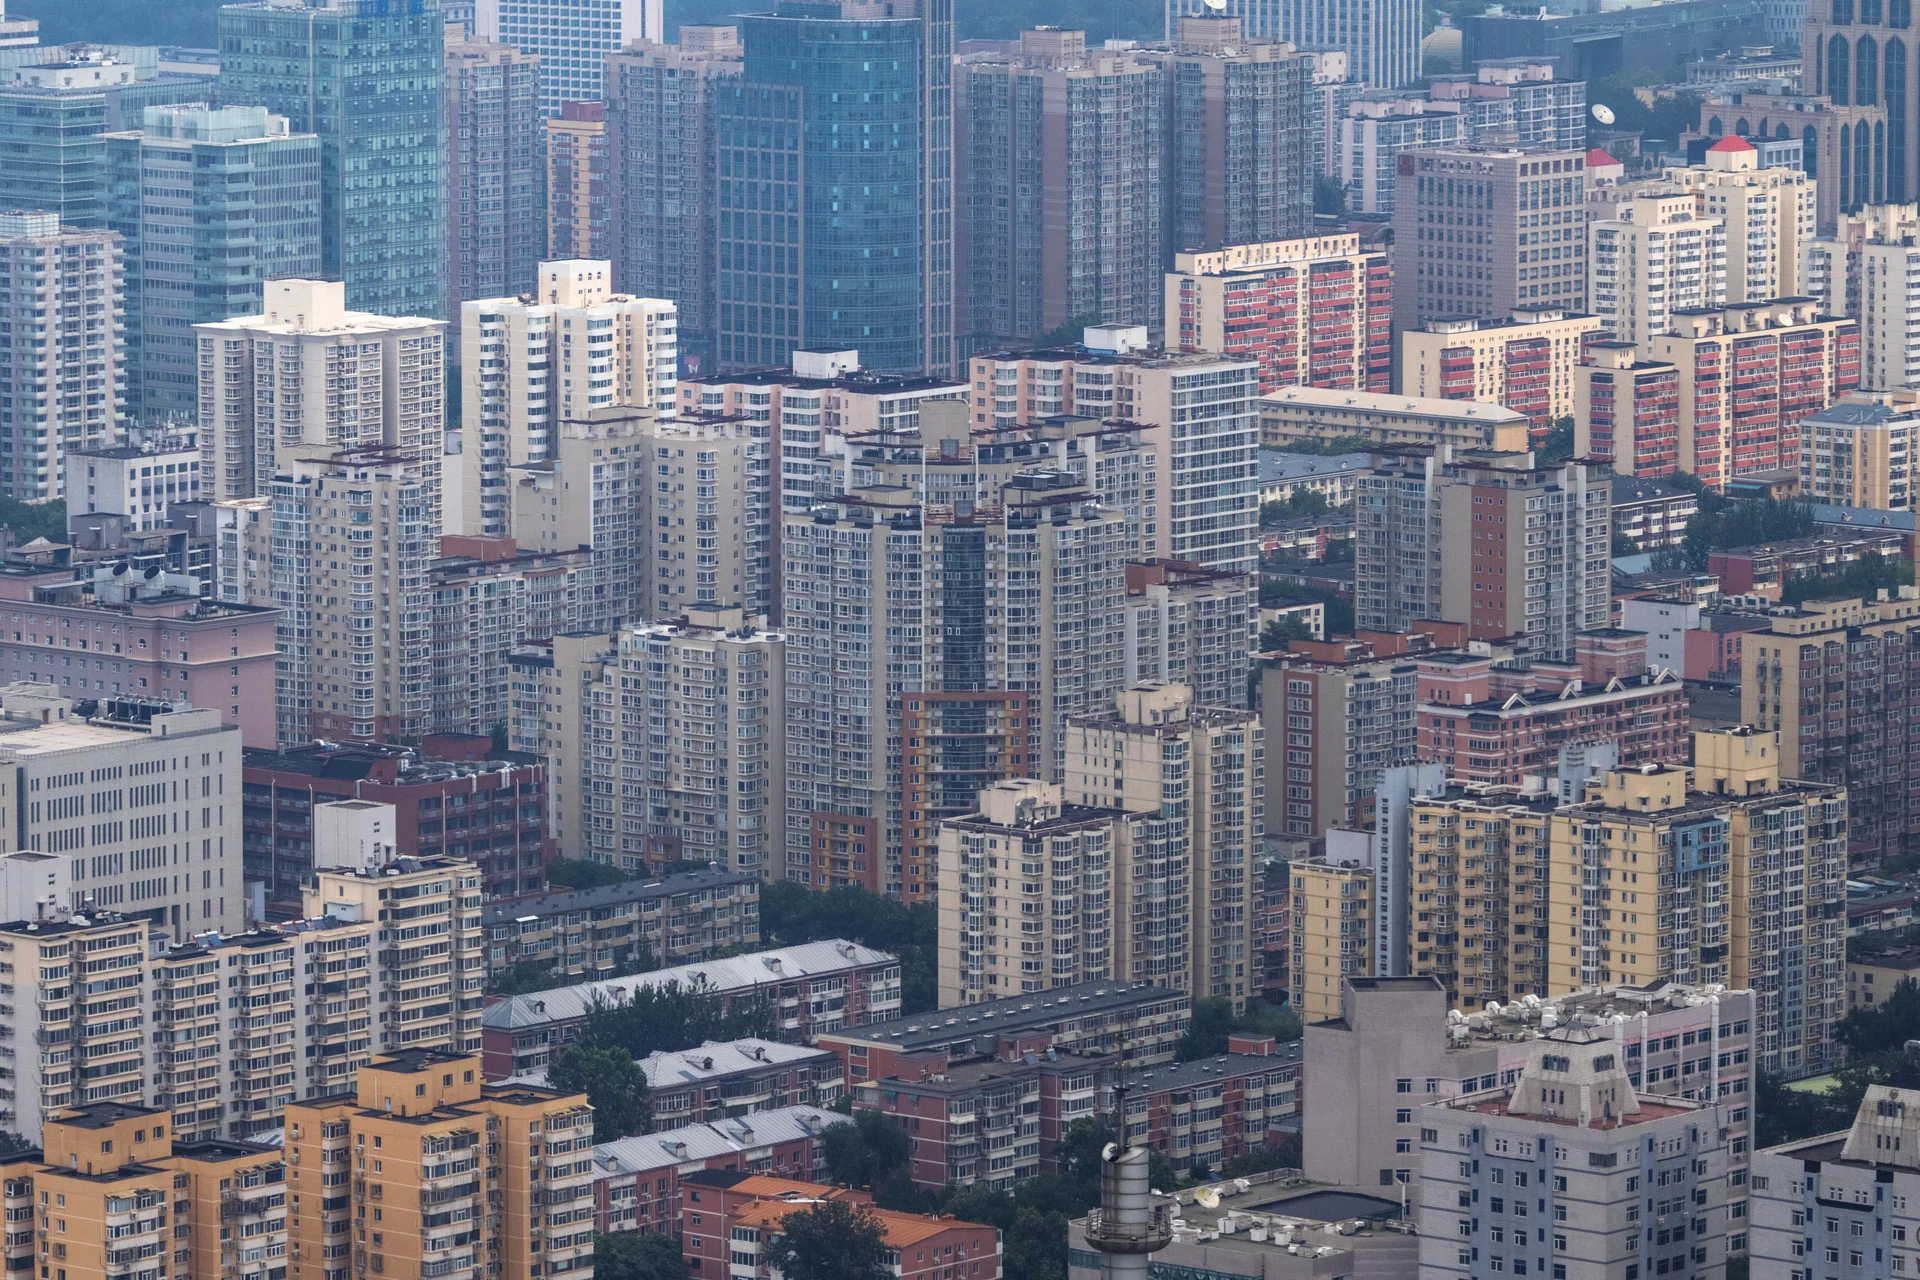
[BEIJING] One of China’s less-publicised avenues for pumping funding into the country’s struggling property market is running into the same problem that has long plagued the industry: supply is overwhelming demand.
The market for publicly listed real estate investment trusts (Reits), introduced in 2021, is showing signs of fatigue, with a glut of deals in the pipeline – more than US$13 billion worth of offerings – set to add to the supply, including two that will begin raising funds in the week ahead.
That deluge threatens to undermine a market that has grown to US$33 billion as Beijing seeks to tap its massive capital markets to fund real estate projects and ease the burden on local governments.
Beijing has been looking for new ways to fund infrastructure projects, including rental housing, traditionally the domain of local government financing vehicles. As the property downturn since 2021 squeezed their cash flows, Beijing has increasingly relied on Reits to recycle some of the investment already in real estate assets.
Among a series of regulatory changes and other fixes, Reits were initially greeted with enthusiasm, particularly as a way to mobilise deep pools of liquidity for infrastructure projects.
Now, they are emerging as the latest corner of China’s capital markets where supply is overwhelming demand, raising questions about the financing tool that has helped shift the cost of funding roads, industrial parks and utilities away from local governments and towards the market.
The struggles expose a mismatch between infrastructure funding needs and low investor interest outside China’s tech ambitions.
“The Reit market slid into a deep correction as a flood of new supply collided with deteriorating fundamentals, unwinding the crowded trades that had supported the sector years ago,” said Zhao Yunjiao, an analyst at CSCI Pengyuan Credit Ratings.
“The result has been a market characterised by low odds of gains and steep drawdowns, disrupting the trading dynamics that once supported the sector.”
Roughly 30 Reit products are awaiting regulatory approval to raise a combined 90.4 billion yuan (US$13.5 billion), on top of another 3.9 billion yuan of issuance expected in the coming weeks, according to figures compiled by Bloomberg.
The pipeline is equivalent to about 40 per cent of the value of the market’s 89 currently listed products, fuelling concern that investor demand may no longer be deep enough to absorb the steady flow of new offerings, especially as returns have fallen short of expectations.
In the days ahead, the Yinhua Yuehai Water Resources fund will look to raise as much as US$255 million and the Huatai Zijin Huazhu Anzhu fund will price its US$196 million initial public offering.
The queue is still building. New World Development on Thursday (Sep 17) said that it had applied to spin off a Shanghai commercial building to list as a Reit on the city’s exchange pending regulatory approval.
While the trusts are pitched as bond-like investment vehicles that offer stable yields and predictable cash flows, their market performance has undercut that appeal. They have fallen 10.4 per cent over the past six months by weighted average, while only half of this year’s debuts are trading above their listing price.
One example is an E Fund product tied to an industrial zone in Guangzhou, which has lost more than 50 per cent since its 2024 listing, though its annualised dividend yield is still merely 4.5 per cent.
It suffered a net loss of eight million yuan in the first half, and said that tenants remain under financial strain while competition is intensifying.
Oversubscription levels have halved from a year ago. A China Securities Index gauge of Reit products is down 28 per cent from its 2022 peak, and trading has slumped to a quarter of the highs two years ago.
The surge in supply is no accident, even given that weak secondary market backdrop. Regulators have spent years expanding the market, broadening eligibility from industrial parks and office buildings to rental housing, shopping malls, hotels and other commercial assets. A once tightly controlled pilot has matured into a regular issuance programme with streamlined approvals.
More recently, Beijing has cast Reits as a pillar of its new property-financing framework, encouraging issuance backed by rental housing and urban-renewal projects.
Exacerbating the market’s caution, the wave of issuance also coincides with a deterioration in the investment case.
“The concept made sense: unlock capital tied up in assets owned by state firms and local-government financing vehicles and recycle it into new investment,” said Cai Yibin, chief investment officer at Xiamen Chuangzhao Private Fund Management.
“But some assets were packaged too aggressively and listed at peak performance. Once fundamentals like rent and occupancy rate softened, investors started questioning the valuations.”
Among recent listings, the CICC Xiamen Affordable Rental Housing Closed-end Infrastructure Fund offered an annualised cash dividend yield of 2.4 per cent in H1, according to a filing, while the Huatai Zijin Suzhou Hengtai Rental Housing Closed-end Infrastructure Fund yielded just 3.4 per cent.
Backed by assets with operating lives exceeding 50 years, the products offered only a modest premium over the 30-year Chinese government bond yield of 2.15 per cent, leaving little compensation for the additional risks investors assume.
Even the market’s more glamorous sectors have struggled to attract buyers. Data centre Reits have joined shopping malls, logistics parks and highways in trading below investor expectations, with a pair of such funds both trading below their offer price, at annualised cash dividend yields at 4.4 per cent and 3.1 per cent.
While that is higher than the 1.7 per cent on China’s 10-year government bond, it pales in comparison to the 30 per cent gain in the CSI Telecommunication Services Index this year.
“When debuts were generating easy gains, even investors with little interest in Reits piled in. But if prices keep falling after listing, institutions eventually stop participating,” added Cai. “Then issuance becomes difficult and the market risks turning stagnant.” BLOOMBERG
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Singapore’s new data centres must use renewables. Can they overcome the hurdles?