Homeowners Get Flood Insurance Reprieve Ahead of Severe El Niño - Newsweek
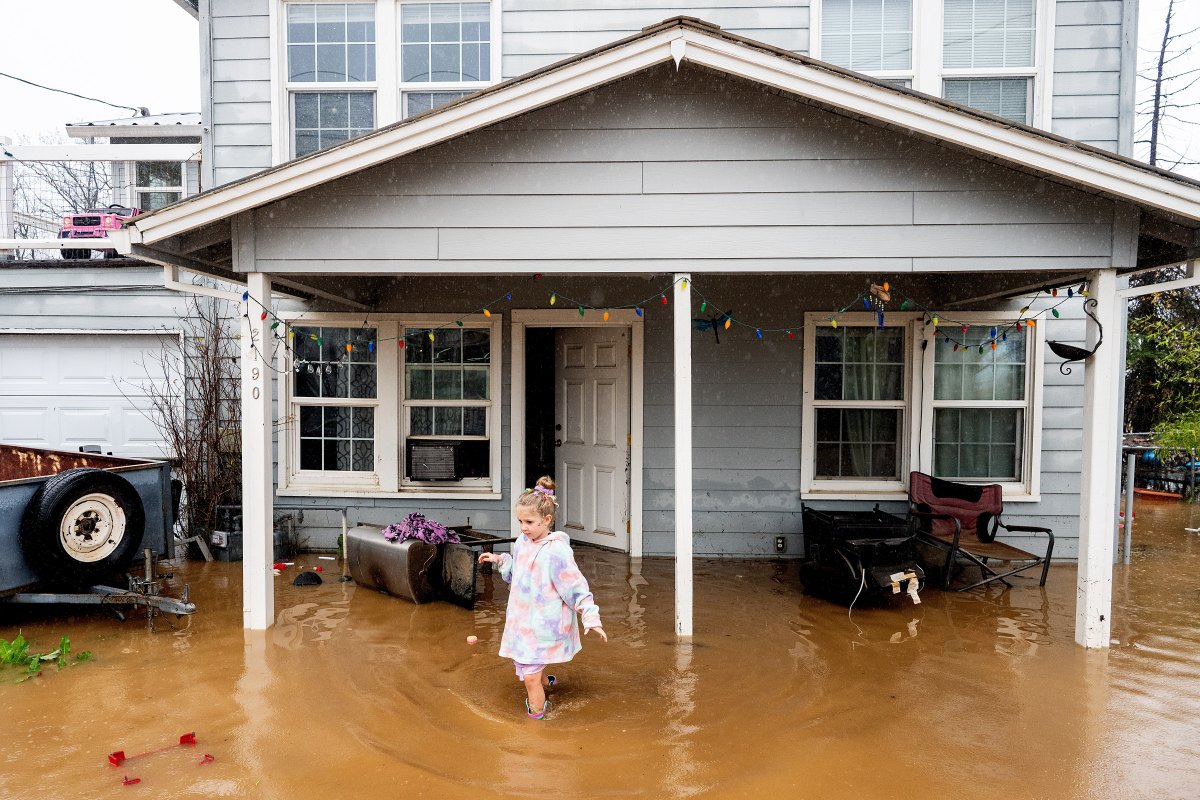
Congress authorized an extension of the National Flood Insurance Program (NFIP), preventing it from lapsing and leaving millions of homeowners without flood coverage this winter, as the country expects to experience the strongest El Niño on record.
El Niño, a naturally recurring climate pattern associated with warmer waters in the Pacific, is set to become “very strong” this fall and winter, according to the World Meteorological Organization (WMO). While the way that El Niño will impact the weather in the U.S. is hard to predict exactly, the phenomenon typically brings “wetter-than-average conditions across the Gulf Coast from Texas to Florida,” climate scientist and meteorologist Tom Di Liberto told Newsweek.
“Wet conditions are also often observed in southern California and the Southwest, especially during stronger El Ninos like the one currently forecast,” he said.
For these regions, a record-strong El Niño is expected to increase the risk of flooding, with potentially catastrophic consequences for homeowners who are not covered by flood insurance.
Experts told Newsweek that the biggest increase in flood risk is expected across California and the southern tier of the U.S., with the threat generally peaking during the winter.
“The southern half of the U.S. is where I’d be watching most closely, particularly California and the Southwest, the southern Rockies, and parts of the southern Plains and Gulf Coast,” Crystal Egger, President of Monarch Weather Consulting, told Newsweek.
“A strong El Niño typically strengthens and shifts the Pacific jet farther south, which can support a more active storm track and increased precipitation across parts of the southern U.S,” Egger added.
For California, “the Sierra Nevada and other higher elevations are particularly important because that added moisture can translate into significant mountain snow when temperatures are cold enough. That snowpack is also critical to water supplies across the West,” Egger said, adding: “I’d also be watching the southern Plains, Gulf Coast and Florida for an increased potential for severe storms, heavy rainfall and strong winds.
"The exact location and timing of those threats will depend on the individual weather pattern as we move through the season.”
Heather Zons, a meteorologist and principal weather producer at The Weather Channel, told Newsweek that Arizona and New Mexico could be especially vulnerable to flooding because mountains, canyons and steep slopes can rapidly channel water into communities and roads.
“We could very easily see rushing water overwhelm dry washes and significantly impact neighborhoods and roads,” she said.
In South Florida, the area’s “sandy soil is perfectly equipped to handle rainfall, however with more and more development on top of those soils, the water has less and less places to go,” increasing the prospect of nuisance flooding, Zons added.
Standard homeowners’ insurance policies do not cover flood damage, making federal flood insurance a lifeline for many. NFIP, which is managed by the Federal Emergency Management Agency (FEMA), provides $1.3 trillion in flood insurance to roughly 4.7 million policyholders in 23,000 communities across the country, according to the latest data.
But even then, far fewer Americans have federal flood insurance or private flood insurance than they should, leaving millions of households exposed to catastrophic damage and enormous financial loss should a natural disaster hit.
Nationwide, only 2.4 percent of homes are covered by federal flood insurance policies, even as 8.4 percent face severe or extreme risk of flooding, according to an analysis by the Associated Press.
That is partly because the cost of homeowners insurance has skyrocketed in recent years all across the country, driven by more frequent and extreme weather events. Especially in the most vulnerable states, like California and Florida, private carriers are struggling to keep up with the increased risk of bigger damages and bigger claims. When unable to raise premiums accordingly, carriers are refusing to renew policies in the most at-risk areas or cutting coverage entirely.
When they do have options for coverage, homeowners are increasingly facing higher premiums, so high in fact that many decide to ditch them entirely and “go bare” when they can, especially when it comes to non-mandatory extras like flood insurance.
The typical cost of a flood insurance policy nationwide is $1,100 per year, up roughly 90 percent in the last five years, according to AP’s estimates.
Within the same period, the count of flood policies with NFIP went down roughly 500,000. At the same time, however, the risk of flooding faced by homes across the U.S. has increased, driven by climate change.
FEMA flood maps determine who is in a high-risk area where flood insurance must be attached to a federally backed mortgage, but many say the maps are not updated and leave out areas now considered at risk. Between 2014 and 2024, official metrics showed that 29 percent to 33 percent of all NFIP claims originated from low-to-moderate risk zones; when accounting for total federal disaster assistance requests, over 40 percent of NFIP claims came for outside FEMA’s designated high-risk areas, according to data from the agency.
Should the NFIP’s authorization lapse and fail to be renewed by Congress by 11:59 p.m. on December 11, FEMA would stop selling and renewing policies for millions of properties across the nation.
The lapse would also have an impact on the program’s ability to pay policyholders’ claims. The authority for NFIP to borrow funds from the Treasury will be reduced from $30.425 billion to $1 billion, according to Congress. These funds will be used to pay claims until depleted.
Another short-term authorization would avoid this, but many are hoping for more long-term reform that would stabilize the program and make it more affordable to low-income buyers, including FEMA.
“The level of damage from recent catastrophic storms makes it clear that FEMA needs a holistic plan to ready the nation for managing the cost of flooding under the NFIP,” the agency wrote in an update published on September 28.
FEMA is working on a better system to map risk across the country and is preparing what has been dubbed the “Future of Flood Risk Data,” but the timeline on the project is not clear. Newsweek contacted FEMA for comment by email on Friday.
Contact Newsweek editors on this story: Matthew Robinson and Cristina Diciu.
Correction: The article previously stated that about 40 percent of NFIP claims between 2014 and 2024 came from outside FEMA's designated high-risk areas; the number referred to total federal disaster assistance requests.