When every month feels like an emergency, can financial literacy really help? - CNA
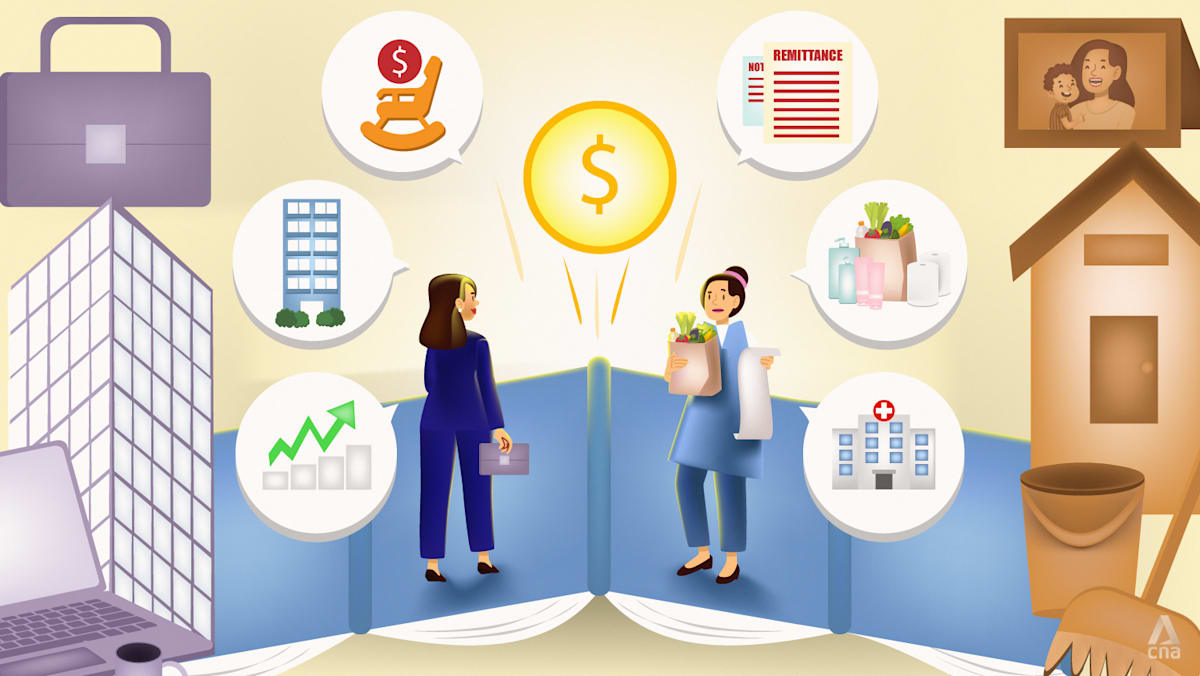
Financial education cannot make up for insufficient income. But it can help people navigate difficult trade-offs and make the most of what they have, writes Jacqueline Loh, CEO of charity Aidha, which helps migrant workers and other low-income earners.
Financial education can be even more important when someone has little margin for error, writes Jacqueline Loh. (Illustration: CNA/Teha Muhamad)
This audio is generated by an AI tool.
Jacqueline Loh 12 Sep 2026 09:30PM (Updated: 13 Sep 2026 10:33AM) Bookmark Bookmark Share WhatsApp Telegram Facebook Twitter Email LinkedIn Set CNA as your preferred source on Google Add CNA as a trusted source to help Google better understand and surface our content in search results. Read a summary of this article on FAST. Get bite-sized news via a newcards interface. Give it a try. Click here to return to FAST Tap here to return to FAST FAST In my work providing financial education to lower-income Singaporeans, a participant in one of my courses once asked point-blank: "How can I save for an emergency when every month is an emergency?"
It was a difficult but very real question.
When you're the main breadwinner and unexpected expenses keep coming up, it can feel like that for many of the people we work with, including migrant domestic workers.
There was no quick tip on budgeting or lesson on how to better distinguish needs from wants that could adequately address the reality of her situation.
CNA Games Guess Word Crack the word, one row at a time Buzzword Create words using the given letters Mini Sudoku Tiny puzzle, mighty brain teaser Mini Crossword Small grid, big challenge Word Search Spot as many words as you can Show More Show Less This was someone doing everything she could just to keep her household afloat.
We often talk about good financial habits as something that begins with a surplus. Conventional wisdom tells us to build up a savings buffer, however small, that allows us to make better money moves – build an emergency fund, for example, or start investing early.
But what if basic monthly expenses already require you to scrimp and save every dollar?
For households operating on razor-thin margins, an unexpected medical bill or a broken appliance is not simply an inconvenience. It can mean having to decide which other expense, however critical, has to wait.
In fact, the less room you have in your budget, the more consequential each financial decision can become.
This is precisely why we should question a common assumption about financial education: that it becomes relevant only when you have more money to manage.
When there is a healthy financial cushion, a poor decision can be absorbed. When there is almost none, that poor decision can reverberate for months, or even years.
When we think about being "good with money", we often think about making money work harder: comparing mortgage rates, maximising credit-card rewards, learning investment strategies and calculating whether we are putting enough aside for retirement.
But for someone on a modest or low income, financial literacy serves a different, more immediate purpose.
The question, then, is not simply how to make your money grow, but rather, how to make the choices available to you count.
If you have only S$200 (US$158) but need to cover S$350 worth of obligations, the issue isn't a simple arithmetic problem, but a high-stress decision-making puzzle – and every choice comes with a consequence.
Do you miss an instalment and incur late fees? Delay paying an insurance premium and risk losing that coverage? Or borrow the difference, knowing that the interest on that loan could leave you with an even bigger shortfall next month?
These are not simple questions to answer.
Take borrowing, for example. For people with limited incomes and little financial buffer, the decision is not simply whether to take a loan to make ends meet.
It can mean weighing an urgent need against the cost of borrowing, considering whether repayments can be sustained alongside everyday expenses, and grappling with fees or terms that may not be obvious at first.
When money is already tight, scarcity can make these trade-offs even harder to assess.
Behavioural economists sometimes call this a "scarcity tax", where immediate financial pressures consume mental bandwidth that could otherwise go to planning or more strategic decisions.
In this state, financial literacy isn't about magically finding another S$150 to plug the gap.
What it can do is help you decide how to use the S$200 in a way that minimises the longer-term damage.
It also provides the analytical framework to compare these competing pressures, reducing cognitive overload so you can better decide which option is likely to leave you least badly off.
A key step is understanding exactly where your money is going.
At Aidha, in our work with migrant domestic workers and low-income Singaporean women, we have found that something as simple as expense tracking can reveal patterns that are hard to notice if you consider only each expense on its own.
For example, many of our migrant domestic worker students regularly send a fixed amount home to their families. But throughout the month, they may also receive requests to send "top-ups" of an extra S$50 or S$100, sometimes more, to their children.
Some of these top-ups are discretionary, such as extra allowance for social activities with friends or a new phone, but many are harder to avoid, including school-related expenses such as field trips, out-of-town events and extra-curricular activities.
Each stand-alone top-up may seem manageable at the time. But it is only after tracking them over time that some of them realise how much these ad hoc payments add up to.
For these women, the lesson is not necessarily to stop supporting their families altogether.
Instead, it is taking proactive steps that will allow them to see the total spent in black and white, allowing them to make a more deliberate decision about how much they can afford to remit each month and how to respond to additional requests without jeopardising their own financial goals.
More importantly, seeing the numbers on paper provides clarity. It transforms money from a source of constant anxiety into something structured and manageable.
The same principle can be applied to other expenses. A few dollars spent here and there may or may not be something you want to cut.
The point of tracking is to first see what those choices cost you collectively, so you can decide whether the money is going toward what matters most to you.