Widow in a legal battle after Eskom death benefit drops from R5m to R4.7m - IOL
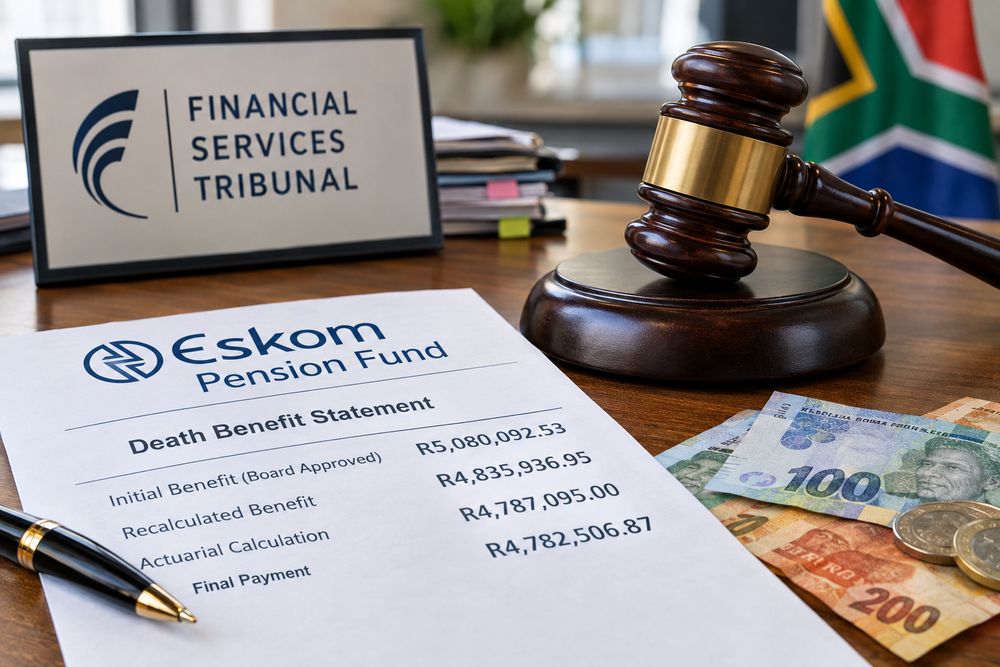
A widow has been left seeking clarity over the calculation of her late husband's Eskom pension death benefit after the amount initially approved at more than R5 million was subsequently recalculated to about R4.7 million.
The Financial Services Tribunal has now set aside a decision by the Pension Funds Adjudicator that had dismissed L Crawford's complaint over the quantum of the death benefit payable to her following the death of her husband, I Crawford.
The late husband was a deferred pensioner of the Eskom Pension and Provident Fund. He had been employed by Eskom from July 1988, until his resignation in July 2021.
He remained a deferred member of the fund until his death in April 2022.
A board resolution allocated 100% of the death benefit to the wife as the sole beneficiary.
The fund initially calculated the death benefit at R5 million including investment returns from the time Crawford became a deferred member until his death.
The board confirmed the amount on April 19, 2023, and Crawford was informed that the benefit would be subject to tax deductions.
However, the fund later discovered that interest had incorrectly been added beyond Crawford's date of death.
It recalculated the investment value at over R4.8 million while an actuarial calculation placed the benefit at R4.7 million.
The final benefit paid to Crawford was R4.7 million. The fund said the difference between the recalculated amount and the actuarial figure resulted from interest being added for April 2022, despite Crawford having died on April 1.
The widow received R3.2 million in December 2024, and over R369,000 in October 2025. The amounts represented the balance after tax deductions.
Crawford subsequently challenged the revised calculation, raising concerns about the lack of complete documentation and transparency surrounding the recalculation.
She argued that she had requested complete and authentic benefit statements to verify the disputed amounts, but that some of the documents had not been provided.
The statements supplied to her covered 2011, 2012, 2014, 2015, 2017, 2018 and 2020.
However, statements for 2013, 2016, 2019, 2021 and 2022 remained outstanding.
Crawford argued that the missing statements, together with inconsistencies in dates and amounts, made it impossible for her to accept the fund's revised figures.
She pointed to three different figures provided during the process: R4. 835 million, R4.787 million and R4.782 million
She also disputed the evidentiary value of an Excel spreadsheet supplied by the fund in relation to the missing financial records.
The fund told the Tribunal that the missing benefit statements could not be retrieved from its system. It maintained that the fund rules permitted an actuary's estimate to form the basis for calculating pension benefits.
It also argued that benefit statements were not promises that the amounts reflected in them would ultimately be paid, describing the figures as non-binding estimates.
The tribunal found that the fund had communicated the board-approved lump sum of R5 million before the amount was subsequently corrected twice.
It also found that the various calculations had been made without the benefit statements for the five outstanding years.
Although a spreadsheet relating to the missing financial information was later provided to Crawford, the spreadsheet was not included in the record before the Tribunal.
The fund also clarified that the spreadsheet was not intended to reconstruct the missing benefit statements.
The tribunal said these circumstances meant that the accuracy and substantiation of the recalculations were in doubt.
"The question of whether the recalculations were accurate and properly substantiated by complete, reliable and authentic supporting evidence is in doubt," the tribunal found.
The tribunal further noted that the Pension Funds Adjudicator's decision did not engage with the quantification process.
Crawford accepted that she was not entitled to an overstated benefit caused by the fund's error in calculating interest beyond her husband's date of death.
Her challenge, however, was based on what she described as a lack of transparency, conflicting figures and the absence of complete and reliable financial statements for five years.
The tribunal found that the board had not had the spreadsheet containing information relating to the missing financial statements when it considered the benefit.
It further found that the Pension Funds Adjudicator had not had all the material documents when determining Crawford's complaint.
The fund indicated that it was willing to engage directly with Crawford to explain the methodology and figures behind its final calculation of R4.835 million
The tribunal said the fund should explain how the spreadsheet was formulated and demonstrate how the authenticity and accuracy of the information relied upon had been established.
It found that Crawford's complaint about the assessment process was warranted.
The tribunal ultimately upheld her application for reconsideration.